Options Analytics
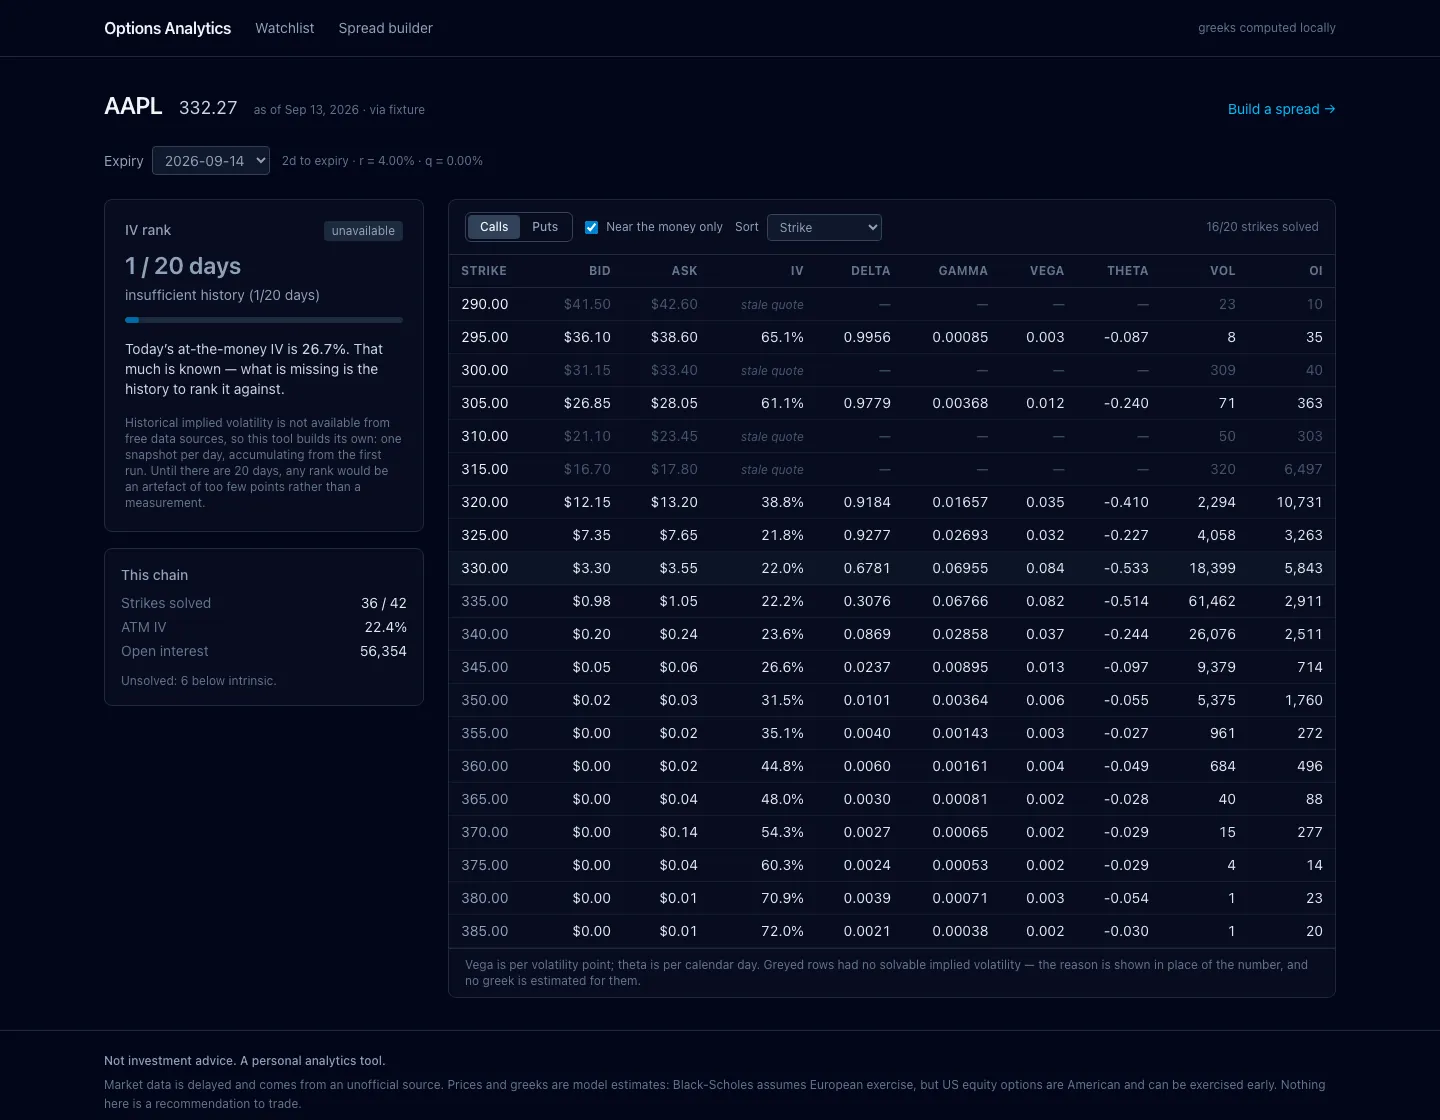
Full-stack options analytics that computes implied volatility and all five greeks itself and builds its own IV history.
Solo · Sep 2026
Rate fixed at 5%, no dividend.
call price
10.45
- Δ Delta
- 0.637
- Γ Gamma
- 0.0188
- ν Vega / vol pt
- 0.375
- Θ Theta / day
- -0.018
- ρ Rho / rate pt
- 0.532
Illustration, not market data. Same Black-Scholes-Merton formulas as the project's pricer, run in your browser.
- Black-Scholes-Merton pricer with a Newton-Raphson IV solver and a bisection fallback; the price → IV round trip is tested to 1e-8.
- Daily snapshots build the history behind IV rank, which says "insufficient history" instead of showing a fake zero.
- 548 Python and 48 TypeScript tests; 97% measured coverage on the analytics core, with CI gating it at 90%.
- Python
- FastAPI
- SQLite
- SQL
- Next.js
- React
- TypeScript
- Docker
- pytest
- GitHub Actions
- Git
- Pandas
- NumPy